Coface has released its latest global Risk Review, revealing a multi-speed global economy facing renewed inflationary pressures, higher commodity prices, and tighter monetary conditions. Against a backdrop where geopolitical developments have shaved an estimated 0.5 percentage points off global growth, moderating worldwide economic activity to 2.5% in 2026 before stabilizing at 2.6% in 2027. GCC economies continue to demonstrate resilience through active rerouting of trade flows and sustained non-oil momentum.
In its quarterly review, Coface carried out four country upgrades and three regional reassessments, alongside 20 sector adjustments worldwide. As global financial conditions tighten after major central banks hike policy rates by 25 basis points, regional enterprises are leveraging strong liquidity to navigate international supply chain adjustments.
Key Global & Regional Findings
- Global Growth Benchmark:World economic expansion is forecast at 2.5% in 2026 and 2.6% in 2027, impacted by higher commodity costs and elevated financing rates.
- Energy & Commodity Volatility: Hydrocarbon prices climbed with oil crossing the $100/barrel threshold in September, alongside significant gains in natural gas and agricultural commodities (+40% year-on-year for wheat).
- Monetary Tightening: Federal Reserve and European Central Bank rate hikes contributed to a 6% rise in the US dollar index and a 100+ bps climb in long-term borrowing rates globally.
- Regional Trade Agility: Despite complex maritime logistics, oil export volumes transiting through the Strait of Hormuz rose sharply, with rapid commercial rerouting across secondary logistics corridors.
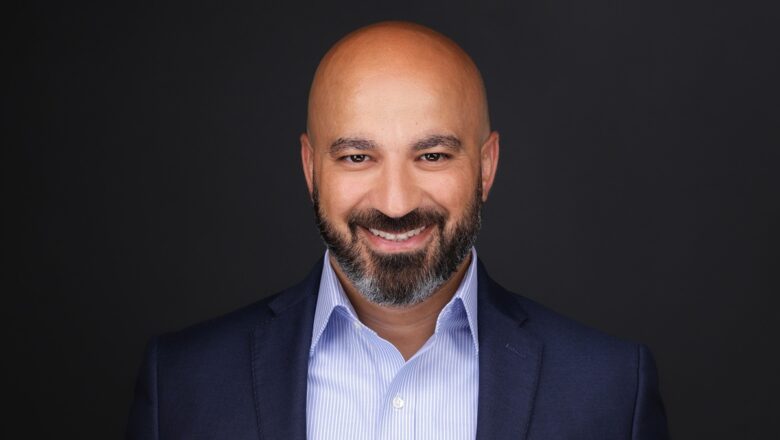
Mohamad Jomaa, CEO and Country Manager for GCC and Egypt at Coface, commented, “While the global economy contends with a prolonged cost-of-capital cycle and growth moderating to the 2.6% mark, the GCC continues to display significant domestic balance-sheet resilience. However, higher energy, freight, and agricultural import costs are spreading globally, so regional businesses must avoid credit complacency. As global supply chains face renewed friction, the priority for GCC enterprises is proactive counterparty intelligence, insulating balance sheets against overseas supplier distress and securing multiple strategic options to support their operation.”
GCC Macroeconomic Focus: Managing Transit Agility and Import Security
Coface’s barometer notes that GCC economies are actively managing external friction originating outside regional borders. In response to short-term transit risks across primary maritime export routes, regional operators have demonstrated operational speed, expanding transhipment volumes and leveraging alternative logistics corridors. Coface’s updated quarterly assessments for Saudi Arabia, the UAE, and Qatar reflect these short-term logistical and transit cost pressures, while highlighting the underlying stability of the region’s fiscal and non-oil frameworks.
In the agri-food sector, Coface’s review highlights international supply lines as a strategic area for commercial monitoring. With global agricultural benchmarks impacted by extreme weather across European farming belts and logistical bottlenecks in Black Sea ports (+40% for wheat), the impact is on international import corridors rather than domestic structural factors. This dynamic reinforces the strategic importance of national food security programs, sovereign reserve storage, and source-market diversification currently underway across the Gulf.